Data study
Best GBPUSD expert advisor: do gold strategies transfer to cable?
 Tommy J.Founder, RoboticEA
The usual advice for finding a GBPUSD expert advisor is to run a search, sort by return and take the top of the list. We ran that search at a scale where the answer stops being an anecdote: 215,727 strategies that had already made money on gold, every one re-run on GBPUSD for each year from 2018 to 2025 (plus the partial 2026) at up to three risk levels, with the recorded spread charged inside the simulation. 5,298,129 backtests. The question is the one every leaderboard silently assumes: does being the best somewhere else tell you anything about being good here?
The short answer
The honest answer
Is there a best GBPUSD expert advisor?
Not one that a backtest can hand you. Pages that rank “the best GBPUSD robots” are ranking in-sample results, and this study is a direct measurement of how much an in-sample rank is worth. We had an unusually clean way to do it: a very large population of strategies whose gold results were already recorded, and a second instrument to run them on. Every strategy keeps the same identity on both, so we can ask, spec by spec, whether the ones that won on gold are the ones that win on cable.
11.7% vs 59.2%
of the same strategies profitable over eight full years: GBPUSD versus gold
Compounded return 2018–2025, 576,050 strategy-and-risk-level records on cable and 534,823 on gold. The gold figure is a selected population by construction: every strategy in the pool made money on gold in-sample. Real recorded spread on both. Engine build 0.2.0.
Everything below is reported as compounded return, because that is the number an account actually experiences. The average of yearly returns is shown once, in the section on why the rank correlation misleads, because it is the figure that flatters the most: on cable, 17.2% of records have a positive average year but only 11.7% compound positive.
Method
What we tested, and how
- The pool is gold’s survivors. Our search on XAUUSD ran 735 rounds and kept every strategy whose in-sample mean year was at least zero. Removing exact duplicates leaves 215,727 distinct strategies (602 duplicates dropped; 132,512 on H4, 83,215 on H1). This is a selected population, and it is the right one for this question: it is what a gold leaderboard is made of.
- Same strategy, different symbol. Only the instrument changes. Each strategy keeps its own timeframe and parameters, and its identity is carried through, so a gold result and a cable result join on the same strategy. That join is the experiment.
- Three risk levels. Every strategy whose sizing can be scaled was run at 2%, 3% and 4% risk per trade; the rest ran once at their own fixed size. That gives 588,681 strategy-and-risk-level records.
- One year at a time. Each calendar year is its own backtest from $10,000, and the yearly returns are then chained. A year counts as rated only if the strategy made at least 10 trades in it; the same rule the product’s verdict uses. 4,359 strategies never reached 10 trades in any year on cable and are counted as flat in the correlations rather than dropped.
- Real recorded spread, plus commission and swap, charged inside the simulation, on real market bars; every run was asserted to be on real bars rather than synthesised ones. Nothing was tuned on GBPUSD.
- Losers were kept. Most studies of this kind keep only what worked. Here the strategies that failed on cable are the measurement, so nothing was filtered on the cable side.
Results
The base rate on cable
11.7%
profitable compounded, 2018–2025
-42.0%
median compounded result
3.2%
earn a “good” or “strong” verdict (gold: 18.8%)
78
profitable in every one of 8 years (gold: 304)
The middle half of results ran from -75.6% to -14.4%, and 43.8% of records lost more than half the account over the period. The median worst-year drawdown was -33.7%, and 28.5% of records had at least one year with a drawdown of 50% or worse. EURUSD, run through the identical experiment, looked much the same (11.1% profitable, median -48.1%), so this is not something peculiar to cable: it is what happens to outside strategies on a cost-bearing major.
Risk per trade: more risk, worse median
| Risk / trade | Profitable | Median result | Median worst-year DD | A year at −50% DD or worse | Records |
|---|---|---|---|---|---|
| 2% | 13.2% | -28.9% | -24.3% | 12.3% | 182,341 |
| 3% | 11.7% | -43.3% | -34.5% | 28.3% | 182,341 |
| 4% | 10.4% | -56.2% | -43.5% | 41.9% | 182,341 |
| own size | 10.6% | -54.3% | -45.7% | 46.4% | 29,027 |
Higher risk did not buy a better result for the typical strategy; it bought a deeper hole. Going from 2% to 4% per trade moved the median compounded result from -28.9% to -56.2% and the share of records with a 50%-or-worse drawdown year from 12.3% to 41.9%.
Year by year
| Year | GBPUSD profitable | GBPUSD median year | EURUSD profitable | Gold survivors profitable | Gold median year |
|---|---|---|---|---|---|
| 2018 | 20.4% | -11.9% | 17.3% | 17.5% | -14.8% |
| 2019 | 56.3% | +2.4% | 34.7% | 34.6% | -5.2% |
| 2020 | 57.4% | +2.5% | 60.6% | 74.9% | +8.7% |
| 2021 | 15.3% | -12.9% | 16.9% | 26.7% | -8.4% |
| 2022 | 25.9% | -10.5% | 26.6% | 34.4% | -5.0% |
| 2023 | 29.0% | -7.2% | 25.1% | 52.9% | +0.9% |
| 2024 | 24.1% | -10.6% | 17.8% | 75.8% | +10.7% |
| 2025 | 34.1% | -4.8% | 46.9% | 86.5% | +21.7% |
| 2026 (partial) | 37.1% | -3.2% | 36.6% | 54.0% | +1.0% |
Gold and cable did not move together. The best year for the gold survivors was 2025, when 86% of them made money; that same year, 34% of the same strategies did on cable. Cable had a majority-profitable year only in 2019 and 2020. That is one hint that what carried the strategies on gold was gold.
The experiment
Do gold’s best strategies win on cable?
Rank all 215,727 strategies by their compounded return on gold, take the top of the list, and see how they did on GBPUSD. If a strategy’s gold performance said anything about the strategy itself, the top of the gold list would beat the pool on cable. As a control we drew random groups of the same size from the pool 1,000 times; a “random band” below is where 95% of those draws landed.
| Picked by gold return | Gold median result | GBPUSD median result | Random group median (95% range) | GBPUSD profitable | Verdict rate |
|---|---|---|---|---|---|
| top 10 | +13217% | -98.0% | -73% to -11% | 20.0% | 0.0% |
| top 100 | +1724% | -93.5% | -51% to -28% | 14.0% | 0.0% |
| top 1,000 | +417% | -79.9% | -42% to -35% | 10.3% | 1.3% |
| top 1% | +288% | -74.6% | -41% to -36% | 10.9% | 2.0% |
| top 10% | +89% | -53.0% | -39% to -38% | 11.4% | 2.5% |
| whole pool | — | -38.5% | — | 12.5% | 2.9% |
The strategies at the very top of the gold list made thousands of percent there. On cable the top 10 had a median compounded result of -98%. With only ten strategies the profitable share is too noisy to interpret, so look at the larger groups: the top 1,000 had a median of -80% and were profitable 10.3% of the time. That is below the range random groups produced, so ranking by gold return did not merely fail to help; it pointed slightly the wrong way. On median result the gap is much larger, well outside the random band.
This is not because the top of the gold list is sloppy. It is what an in-sample ranking is: a list of the strategies whose parameters fitted one instrument’s path best. Across the whole pool the rank correlation between a strategy’s gold result and its cable result was +0.26 for compounded return (95% interval +0.26 to +0.27) but −0.20 for the average year. Two clearly non-zero numbers with opposite signs is not what a weak-but-real edge looks like. It is what a confound looks like, and the next section is about it.
Correcting the record
Why the rank correlation fooled us
Two of our earlier posts reported rank correlations between instruments and read them as “close to zero”. The instrument study found a median of +0.402 across instrument pairs and +0.274 for EURUSD against GBPUSD, and the forex robots study found a similar weak transfer. The measurement was fine; the reading was too loose. With 215,727 strategies instead of a few dozen we can see what those numbers were made of.
How busy a strategy is, and how much it swings, are properties of the strategy, not of the instrument. Trades per year carry from gold to cable almost perfectly (rank correlation +0.98), and the year-to-year volatility of a strategy’s returns carries too (+0.77). Compounded return punishes volatility: a strategy that swings hard loses more to compounding than its average suggests. And on cable, where the typical strategy has a negative edge, the swingers are wrecked. A strategy’s volatility on gold predicts its compounded result on cable at −0.70, a far stronger relationship than the gold result itself.
Put those together and both signs make sense. Among gold survivors, the volatile strategies have a high average year (+0.48 with volatility) but a poor compounded one (−0.25). On cable the volatile ones lose either way. So gold’s compounded rank lines up with cable’s (calm strategies are calm on both) and gold’s average-year rank lines up against it (the volatile ones with the big averages are the ones that get destroyed). Neither is skill.
| Decile (gold volatility) | Median yearly swing on gold | GBPUSD median result | GBPUSD profitable | Rank corr. inside group |
|---|---|---|---|---|
| D1 (calmest) | 5.6% | -11% | 22.9% | −0.01 |
| D2 | 9.1% | -18% | 21.3% | +0.02 |
| D3 | 12.3% | -24% | 16.8% | +0.05 |
| D4 | 15.7% | -32% | 14.0% | +0.04 |
| D5 | 19.6% | -39% | 11.5% | +0.07 |
| D6 | 24.2% | -47% | 9.3% | +0.08 |
| D7 | 30.5% | -57% | 6.4% | +0.09 |
| D8 | 39.6% | -68% | 4.7% | +0.13 |
| D9 | 55.3% | -81% | 3.0% | +0.27 |
| D10 (wildest) | 104.6% | -98% | 1.4% | +0.65 |
Inside the calmest tenth of strategies the gold-to-cable rank correlation is −0.01; inside the wildest tenth it is +0.65. The whole-pool figure is mostly the wild end talking. And the share that make money on cable falls from 22.9% in the calmest group to 1.4% in the wildest.
+0.26 → +0.04
rank correlation of compounded return, gold to GBPUSD: raw, then holding volatility and trade frequency fixed
Partial rank correlation controlling for a strategy's gold return volatility and its trades per year. On the average year the same control moves −0.20 to −0.06. A volatility-matched test agrees: comparing strategies of the same frequency and volatility, gold's top tenth was profitable 10.5% of the time on cable against 11.1% for their matched peers.
So the corrected statement is not “the rank correlation is about zero”. It is: the raw correlation is real and sizeable, and it is entirely the volatility and turnover of the strategies; once you compare like with like it is close to zero. The stratified estimate agrees (about +0.04), and the size of the effect is small enough to ignore even where it is statistically distinguishable. The same is true of the cable-to-EURUSD correlation of +0.69 on these strategies: two dollar majors agreeing on which strategies are calm is not evidence that a good one on one is good on the other. The instrument study’s conclusion, that a league table of best pairs is an artifact, stands. Its phrasing (“only” a correlation of +0.402) understated how much of a correlation you can get for free.
Cost
Is it the spread?
Cable is a cost-bearing instrument, so the obvious suspicion is that the strategies lose only because of what they pay to trade. We measured that directly: 200 random strategies (standard sizing, no grids), each run twice on each of gold, GBPUSD and EURUSD at 3% risk over the full years, once with the recorded spread, commission and swap, once with no costs at all. The difference is the friction, per trade, in units of the risk taken.
| XAUUSD | GBPUSD | EURUSD | |
|---|---|---|---|
| Friction per trade (R, median) | 0.054 | 0.028 | 0.029 |
| Friction per year (% of account, median) | 7.0% | 3.7% | 3.9% |
| Profitable over the full years, real cost | 50.0% | 8.7% | 8.4% |
| Profitable over the full years, zero cost | 96.5% | 32.0% | 28.9% |
| Median compounded result, zero cost | +97% | -13% | -26% |
| Median trades per year | 44 | 46 | 45 |
Friction per trade on cable was 0.028 R against 0.054 R on gold, so cable is the cheaper of the two to trade. Costs do matter, since removing them lifted the profitable share on GBPUSD from 8.7% to 32.0%. But even with no costs the median strategy lost 13% over the period, so spread is not the explanation. The strategies do not fit this market. That is the difference between a cost problem, which a cheaper broker fixes, and a fit problem, which nothing does. (Gold’s zero-cost figures are inflated by the pool having been selected there.)
What to look at
Which timeframe, archetype and risk level
| Timeframe | Strategies | GBPUSD profitable | GBPUSD median result | Verdict rate | Gold verdict rate |
|---|---|---|---|---|---|
| H1 | 83,215 | 6.4% | -65.2% | 1.5% | 12.9% |
| H4 | 132,512 | 16.4% | -24.9% | 3.7% | 16.8% |
H4 treated the transplanted strategies less badly than H1: 16.4% profitable against 6.4%, and a median result of -25% against -65%. That matches the mechanism in our timeframe study: the slower chart pays the spread fewer times. It is a statement about cost, not a claim that H4 strategies have an edge on cable.
Archetypes barely separate. The best three by share profitable were Multi-Step (17.1%), Session (15.7%), Stationary Reversion (14.5%); the worst three were Anti-Martingale (6.5%), Volatility (10.2%), Regime Router (10.6%). The whole range is 6.5% to 17.1%, narrower than the gap between the two timeframes. By how the position is sized, expression-sized strategies did worst (median -67%, 9.9% profitable) and fixed-lot strategies best (-11%, 17.5% profitable). Treat the fixed-lot result with suspicion: it is the one group where gold’s ranking did carry over to cable, and it is dominated by grid-style baskets of limit orders, the strategy class where a backtest engine is least likely to match live fills. A result that transfers between instruments for a reason that would also transfer between a simulator and a broker is a warning, not a discovery.
On risk, the table above already says it: the median result gets worse at each step up in position size. If you run any of these ideas, the smallest risk level in this study is the one that lost least.
The best on cable
The best GBPUSD strategies we found
Naturally we looked at the other end too: which strategies were best on cable itself. We limited this to ordinary strategies (ATR-based or risk-percent sizing, no grids, no state machines), that traded in every one of the 8 full years with at least 20 trades a year on average, and that ended up profitable. 35,689 records qualified out of 576,050. These are the top of that list, with every year on show.
Read this as an illustration of a selection trap, not as a recommendation. These were chosen because they did best on the years we then show, from a pool of 576,050 records. That is a search across 576,050 tickets, and the top of any such list looks good in the years it was picked on. The next section tests exactly that.
| Strategy | ’18 | ’19 | ’20 | ’21 | ’22 | ’23 | ’24 | ’25 | ’26* | 8-yr compounded | Worst-year DD |
|---|---|---|---|---|---|---|---|---|---|---|---|
| d452_Microstructure_46 · H1 · 4% risk | +37.1% | +30.9% | +95.1% | -2.6% | +4.0% | +105% | +8.1% | -11.6% | -34.0% | +595% | -44% |
| d594_Cycle_52 · H1 · 4% risk | +136% | +96.6% | -41.3% | -23.3% | -24.4% | +55.3% | +32.5% | +86.4% | -10.4% | +504% | -63% |
| d8_Trend_Gate_4 · H1 · 4% risk | +18.8% | +30.7% | +41.1% | +7.3% | +12.8% | +35.1% | +52.2% | +1.7% | +5.7% | +454% | -32% |
The strongest of these did make +595% compounded, but with 6 profitable years out of 8, a worst year of -12% and a worst-year drawdown of -44%. The tidiest one (d8_Trend_Gate_4) was profitable in all 8 years, at +454% compounded, and it traded about 23 times a year. Only 36 records met that bar with our trade floor. If each year were an independent coin weighted by that year’s share of profitable results, we would expect about 31 to do it by luck across the 500,185 records with all 8 years rated, before any trade floor. A clean record is not much rarer than chance would produce.
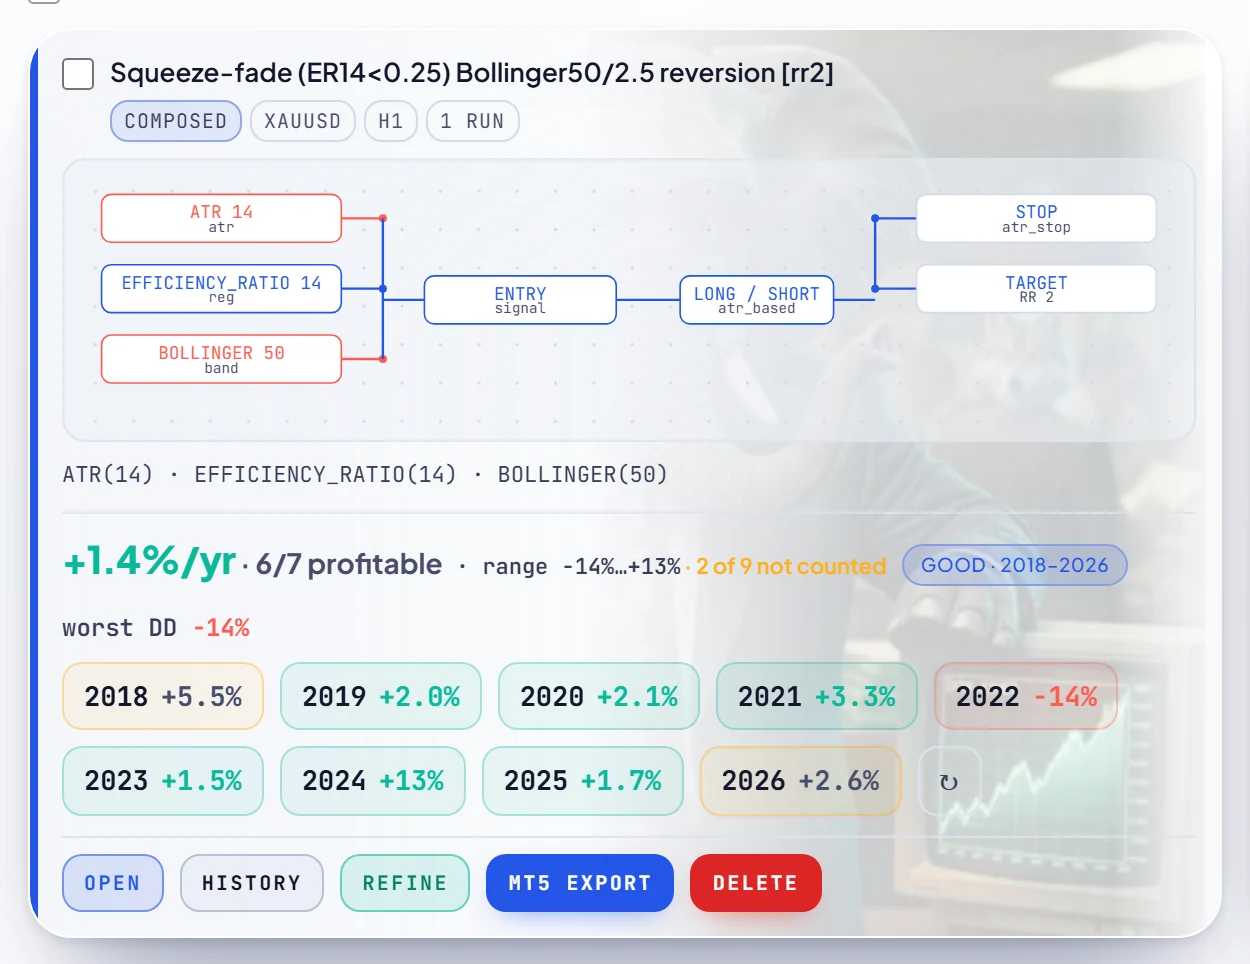
We also excluded stand-out records (3,206 that passed the same filters but use fixed lots, expression sizing or hooks). Their top rows are session-anchored limit-order baskets taking well over a thousand trades a year with tiny drawdowns, and martingale-style sizing. Their own strategy descriptions warn that grid-basket behaviour is the class we match least closely against MetaTrader 5’s tester, so we do not present them as tradeable results. The top of that list was d227_Martingale_51 at +2266%.
The holdout
…and the test that removes them
Here is the test. Pretend it is the end of a training period: pick the best ordinary strategies on cable using only the years up to then, and score them on the years that followed, which they never saw. We ran 5 such splits (the pick uses the years up to the cut-off, the score uses the two after) and, for the 2018-2023 to 2024-2025 split, a picked group of the top 100 made a median -51% on the unseen years, against a random group of the same size’s -16% to -7%.
| Trained on | Scored on | Eligible | Pool median, unseen | Top 100 median, unseen | Top 1,000 median, unseen | Train→test rank corr. |
|---|---|---|---|---|---|---|
| 2018-2019 | 2020-2021 | 131,074 | -10.9% | -53.2% | -42.5% | −0.20 |
| 2018-2020 | 2021-2022 | 161,455 | -22.0% | -77.0% | -66.7% | −0.28 |
| 2018-2021 | 2022-2023 | 90,261 | -14.0% | -54.5% | -44.8% | −0.20 |
| 2018-2022 | 2023-2024 | 71,282 | -14.6% | -67.0% | -52.0% | −0.26 |
| 2018-2023 | 2024-2025 | 53,202 | -11.3% | -50.9% | -36.1% | −0.19 |
In every split the picked strategies did worse than a random group, not better, and the rank correlation between training-period return and later return was negative in all of them (−0.28 to −0.19). Selecting on cable’s own past picked strategies that had been lucky, and luck does not repeat. Choosing by gold’s past did not do better: in the 2018-2023 to 2024-2025 split, the top 1,000 by gold’s training-period return made a median -31% on cable’s unseen years, with the pool at -11%. Selecting instead for a “clean record” (every training year profitable) did better than picking at random: the group’s median beat the random range in 4 of 5 splits. But the median result on the unseen years was still a loss in every split (-13% to -7%), with 21% to 31% of the group profitable. A clean record is a modest improvement in the odds, not a way to find a profitable cable strategy.
That is the shrinkage, and it is the point of the whole study. The strategies in the grid above look like answers. The holdout says they are the best of a very large draw, and the best of a large draw is mostly the largest piece of luck. If you take one thing away: a backtest ranking, on any instrument including the one you trade, is the start of an investigation.
Test your own idea the same way
RoboticEA runs any strategy on GBPUSD, or any of our other instruments, one year at a time with the recorded spread charged inside the simulation, so the losing years are on the page before you trust the total.
Limits
What this does not show
- The pool is gold’s survivors. Only strategies with a non-negative in-sample mean year on gold were re-run. The cable base rate here is the base rate for strategies that passed a gold filter, not for strategies in general. Cutting off gold’s losers also compresses the gold side of every correlation, which is why we lean on the top-of-the-list tests and the holdouts rather than on any single correlation.
- Best-on-cable is in-sample. The strategies in the grid were selected on the same 8 years they are shown for, from 576,050 records. They are a picture of a selection trap. They are not a shortlist to trade, and the holdout is why.
- Gold and GBPUSD share a currency. Both are priced against the US dollar, so the same year can move both. The years are not independent evidence, and the by-year gold-to-cable correlations swing enough to show it.
- 2026 is a partial year and is left out of every headline figure and every compounded number; it is shown only where marked.
- Each year is an independent backtest from $10,000, chained afterwards, not one continuous account. Drawdowns are within-year, and a real account would also feel the ones between years.
- This is a backtest, not live trading. The engine is checked against MetaTrader 5’s own tester on our parity study, but a simulation is not a fill on a live account, and grid-style strategies match least closely. Costs are the recorded spread plus commission and swap; slippage on a fast market is not the same.
- The cost probe is small (200 strategies per instrument). Read its shares as good to a few points.
The numbers on this page come from 5,298,129 runs on GBPUSD and the same pool on EURUSD, all on real market bars, one engine build, produced by a script that reads the raw per-year rows rather than any summary. That script re-derives the product’s own verdict on every strategy the ranker saved and agrees with it exactly, which is our check that the year-by-year figures here are the same ones you would see in the app.
FAQ
GBPUSD EA questions, answered
Is there a best GBPUSD expert advisor?
Not one a backtest can hand you. We re-ran 215,727 strategies that had already made money on gold on GBPUSD for each year from 2018 to 2025, with the recorded spread charged inside the simulation, and only 11.7% of the 576,050 strategy-and-risk-level records were profitable compounded over the eight years (the same strategies on gold: 59.2%). The median result was -42.0%, 3.2% earned a good or strong verdict, and only 78 were profitable in every one of the eight years. The best in-sample GBPUSD strategies did not hold up on years they were not picked on, so treat any ranking as a shortlist to investigate.
Do gold strategies work on GBPUSD?
Not in this test. We ranked 215,727 gold-selected strategies by their compounded return on gold and scored the top of the list on GBPUSD. The top 1,000 were profitable 10.3% of the time on cable, against 12.5% for the whole pool and a random-group range of 10.5% to 14.5%, and their median compounded result was -79.9% against -38.5% for the pool. The rank correlation between gold and cable results looks positive for compounded return (+0.26), but that is strategy volatility, not skill: holding volatility and trade frequency fixed it falls to +0.04.
Which timeframe is better for a GBPUSD EA, H1 or H4?
H4 treated the transplanted strategies less badly. 16.4% of H4 strategies were profitable compounded over the eight full years against 6.4% of H1 strategies, and the median result was -24.9% on H4 against -65.2% on H1. The mechanism is cost: the slower chart pays the spread fewer times. It is not evidence that H4 strategies have an edge on cable, since the median H4 strategy still lost money.
How much risk per trade should a GBPUSD robot use?
In this study the median result got worse at every step up in risk. At 2% risk per trade the median compounded result over the eight full years was -28.9% with 13.2% of strategies profitable; at 3% it was -43.3% (11.7%); at 4% it was -56.2% (10.4%). The share of strategies with at least one year of a 50% drawdown or worse rose from 12.3% to 41.9%. This describes outside strategies on cable, not advice about sizing your own.
Is it the spread that makes GBPUSD hard for an EA?
Only partly. We ran 200 random strategies twice on GBPUSD, once with the recorded spread, commission and swap and once with no costs, and the median friction was 0.028 R per trade (units of the risk taken), against 0.054 R on gold. Removing costs lifted the share profitable over the eight full years from 8.7% to 32.0%, but the median strategy still had a compounded result of -13% with no costs at all. Cost hurts; the larger problem is that strategies fitted on one instrument do not fit another. The cost probe is small, so treat the shares as good to a few points.
Can I pick the best-backtested GBPUSD strategy?
The best backtested ones did not hold up. We picked the top strategies on GBPUSD using only the years up to a cut-off and scored them on the following years; in the 2018-2023 to 2024-2025 split the top 100 made a median -51% on the unseen years, against -16% to -7% for random groups of the same size. Across all 5 splits the rank correlation between training-period and later return ran from -0.28 to -0.19, so in-sample rank on cable was, if anything, anti-predictive. The strategies with the best cable record are an illustration of that selection effect, not a shortlist.
Does an EA that was profitable in all eight years stay profitable?
A clean record helps a little, but it is not a guarantee. Of 576,050 strategy records on GBPUSD, only 78 were profitable in every one of the eight full years, and 36 of those also averaged at least 20 trades a year with ordinary sizing; treating each year as an independent draw at its own profit share, about 31 would be expected by luck among the 500,185 records with all eight years rated. In the holdout, picking strategies whose every training year was profitable beat a random pick on the median in 4 of 5 splits, but the median result on the unseen years was still a loss in every split (-13% to -7%, with 21% to 31% of the group profitable). A clean record is a reason to test further, not a reason to trade.
Keep reading
Best forex pairs for expert advisors
What each of 25 instruments charges a strategy, and why a best-pair league table is an artifact. This post refines its rank-correlation reading.
Do forex robots actually work?
The prior question over the same engine: how often an automated strategy survives at all.
Best gold expert advisor for MT5
Where the strategies in this study came from: the gold search, year by year, on real spread.
Best timeframe for expert advisors
Why the slower chart pays the spread fewer times, measured separately.